Business expansion loans for growing UK SMEs: sizing, structure and speed
A practical guide to funding UK business expansion: choosing the right structure for the growth thesis, sizing the facility, and getting through underwriting cleanly.
What counts as expansion capital
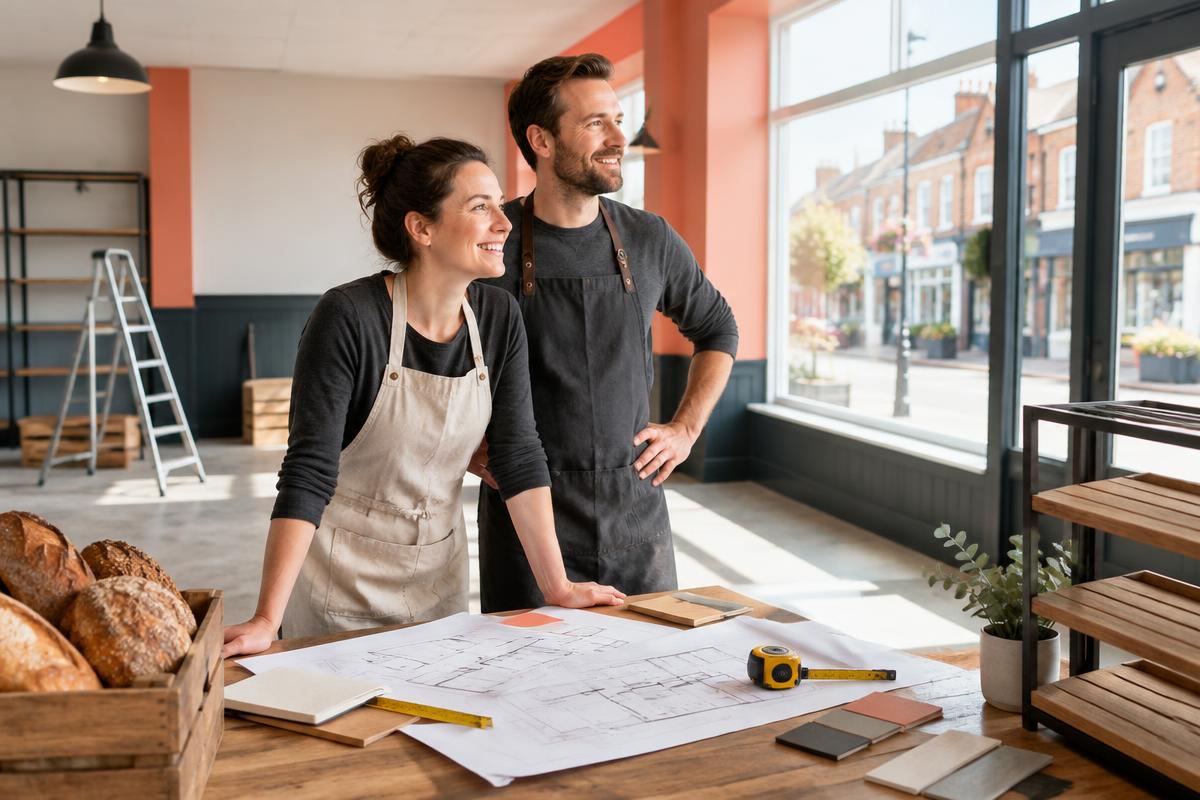
Expansion capital funds growth you have already tested, a second site, a new hire cohort, additional kit, expansion into a new region, not speculative launches. Underwriters price expansion much better than start-up risk.
The evidence that unlocks the cleanest terms is trading history that already demonstrates the model works: unit economics that survive at scale, a customer base that renews, a P&L that supports servicing.
Choosing the right structure
Fixed-term business loans (3–24 months) suit projects with a clear payback horizon and predictable monthly cost, a fit-out, an equipment build, a hire cohort.
Secured business loans against property or plant suit larger, longer expansion where sharper pricing matters, often the right tool above £250k.
Revenue-based finance suits subscription and e-commerce operators where the expansion feeds monthly revenue directly.
Common structuring mistakes
Matching a 24-month payback to a 6-month facility (repayment strangles the very growth you funded). Under-drawing to keep monthly cost down (running out mid-project is more expensive than borrowing the right amount once).
Stacking multiple small facilities instead of consolidating into one structured loan (blended cost creeps up; covenants overlap).
Prove the expansion can carry its own capital
Build a complete project budget
Include deposits, professional fees, fit-out, equipment, recruitment, training, opening stock, launch marketing and cash needed before break-even.
Separate existing and new trade
Show that the current business can continue meeting its commitments if the new site, team or channel starts later than planned.
Set decision gates
Tie spending to milestones such as lease completion, planning, signed orders, hiring or equipment installation rather than drawing everything at once.
Application checklist
- Costed project plan
- Monthly forecast and downside case
- Existing-site management accounts
- Lease or supplier terms
- Hiring and opening timetable
- Break-even and repayment source
Useful primary and industry references
These references support further research. Product terms and official guidance can change.
Frequently asked
How much can I borrow for expansion?
The available amount depends on affordability, trading history, existing commitments, the use of funds and any security. Compare the amount needed with a downside cash-flow forecast rather than starting from a provider's maximum.
Will I need a personal guarantee?
A provider may request a personal guarantee depending on the amount, product and risk assessment. Read the scope and cap carefully and obtain independent legal advice before signing.
How fast can expansion funding be drawn?
Timing varies by file. Secured facilities usually need additional valuation and legal work, so build that process into the expansion timetable.